Tax planning strategies should be tailored to an individual’s unique financial situation, goals, and sources of income. Consulting with a qualified tax professional or financial advisor can help individuals make informed decisions to minimize their tax liability and maximize their financial well-being. For subscriptions or ongoing services, divide the total payment by the number of service months to see your monthly earning rate and what you still owe. Build systems that capture every prepayment at the transaction level. Link each payment to specific performance obligations and https://pagmedica.com/bookkeeping/2026-fremont-california-sales-tax-calculator-rate-2/ delivery schedules.
Is Unearned Revenue a Liability?
When unearned revenue is tracked and managed effectively, it reflects not only strong demand for your products or services but also your company’s ability to deliver on its promises. Your company has made a commitment to your customers, and until you deliver on that promise—be it a service or a product—you owe them. It’s like holding onto someone else’s belongings until you fulfill your part of the deal.
Find the value hiding in your business
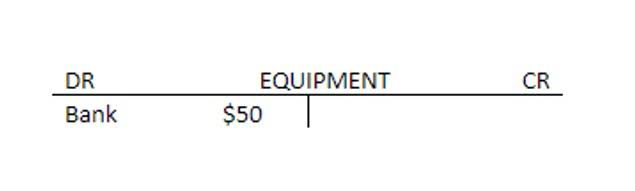
That’s why unearned revenue is considered a current liability account under the balance sheet. When a company receives advance payment, it debits cash (more assets) and credits deferred revenue (more liabilities). Deferred revenue is income received in advance of earning it through product delivery or service completion.
Is Unearned Revenue an Asset, Liability, Revenue, or Expense?
You’ve seen the essentials of unearned revenue, but you might still have questions. Unearned revenue appears as a liability because you owe goods or services. Integration with accounting systems like NetSuite and QuickBooks simplifies the entire recognition workflow from billing to payroll financial reporting. Finance teams need immediate access to drill into specific customers or contracts.
- It also makes it easier to automate routine tasks as your business scales.
- This standard, which was issued by the Financial Accounting Standards Board (FASB) in 2014, provides a comprehensive framework for recognizing revenue from contracts with customers.
- You cover more details about computing interest in Current Liabilities, so for now amounts are given.
- The adjusting entry will always depend upon the method used when the initial entry was made.
- Extended licensing deals, involving upfront payments for long-term software use, also contribute to unearned revenue.
- It will be part of the income statement only after the completion of service or delivery of goods.
Although unearned revenue is classified as a liability, it offers invaluable insights into a company’s financial and operational health. By understanding its role, businesses can strategically manage this liability, turning it into a driving force for growth and stability. Understanding and effectively managing unearned revenue is vital for a company’s financial health and strategic decision-making. By accurately tracking, forecasting, and integrating unearned revenue data into broader business planning, companies can ensure financial stability and gain valuable insights for growth. Grasping the concept of unearned revenue is more than just a compliance issue. It’s about understanding the promises your company has made and how they impact your financial planning.
If you have noticed, what we are actually doing here is making sure that the earned part is included in income and the unearned part into liability. The adjusting entry will always depend upon the method used when the initial entry was made. On December 31, 2021, the end of the accounting period, 1/3 of the rent received has already been earned (prorated over 3 months). Since the actual goods or services haven’t yet been provided, they are considered liabilities, according to Accountingverse. While unearned and unrecorded fees can seem minor in the big picture, they should not be omitted. We need to account for those promptly to ensure the accuracy of financial records.
On your balance sheet, unearned revenue is listed under liabilities. This is because you have a duty to either deliver the goods or services, or return the money. Once you fulfil your end of the deal, the liability is removed, and the amount is recognized as earned revenue on your income statement. Deferred revenue shows up on the balance sheet as a current liability.
- This is money paid to a business in advance, before it actually provides goods or services to a client.
- Unearned fees are classified on the Balance Sheet as a Liability account.
- Until the company delivers each month of service, that $12,000 remains unearned.
- When deferred expenses and revenues have yet to be recognized, their information is stored on the balance sheet.
- Its proper recording and reporting are crucial for accurate financial statements and a clear understanding of a company’s financial position.
- We need to record it as unearned revenue because it does not represent income earned.
It can include income charged by professionals, such as lawyers, accountants, consultants, architects, doctors, and other service-based industries. For example, an accounting firm may earn fees for auditing, tax preparation, financial consulting, or bookkeeping services. Understanding the intricacies of revenue recognition, from earned to unearned revenue, is crucial what is unearned revenue for any SaaS company. Valueships.com can be a big help in this field and a pivotal resource in optimizing pricing strategies.
Some examples include interest, and services completed but a bill has yet to be sent to the customer. Accruals are types of adjusting entries that accumulate during a period, where amounts were previously unrecorded. The two specific types of adjustments are accrued revenues and accrued expenses. Remember to record your unearned revenue as a liability so you have a clear picture of how much profit your business is making.
Since there was no bill to trigger a transaction, an adjustment is required to recognize revenue earned at the end of the period. After the first month, the company records an adjusting entry for the rent used. The following entries show initial payment for four months of rent and the adjusting entry for one month’s usage. Accrual accounting is a method of financial reporting in which transactions are recorded when they are incurred, not when the cash is exchanged. This method allows for a more accurate reflection of a company’s financial activities, providing a better understanding of the company’s overall financial health.